Viral Hooks
Trending short videosFinancial rules listicle with examples
M

@mikes.ai

Instagram · Yap
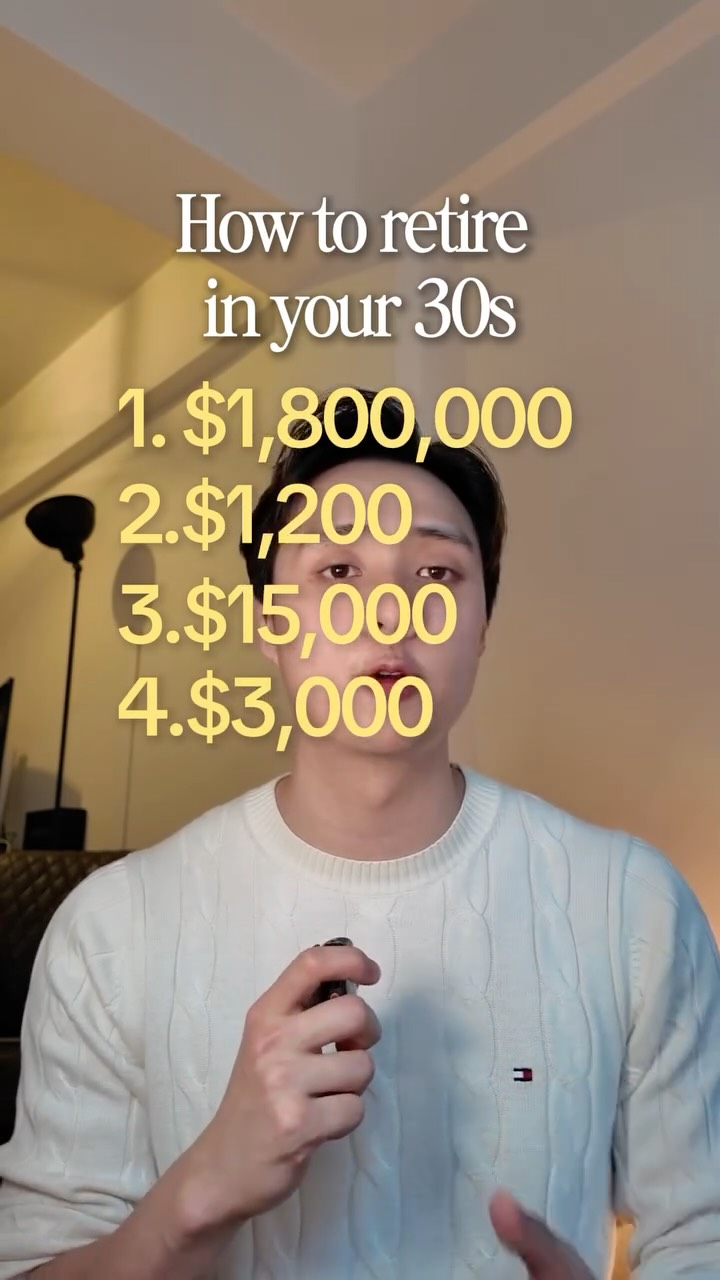
@mikes.ai Four numbers that tell you exactly where you stand and what you need to work on. 1. Monthly income x 300. That’s what you need invested before your portfolio can replace your job, based on withdrawing 4% a year. 2. Monthly income x 0.2. What you should be investing every month. Ten percent is the bare minimum, twenty is what actually moves the needle. 3. Monthly expenses x 6. Your emergency fund, kept in a high yield savings account instead of the market. Use expenses, not salary, or you’ll save more than you need. 4. Monthly income x 0.5. Your ceiling on rent, food, transport and bills. Go over it and every other number here gets harder. Which one are you furthest from? (Not financial advice, do your own research)
View original on Instagram

The edit1 shot · 5 text
Shots Text0:26

Performance

Views
1.1M
Likes
10.1K
Comments
316
Engagement
0.9%
Length · 25 Jul 2026
0:26

Video #46633 · Yap

Financial rules listicle with examplesfrom @mikes.ai

[01]

Overview

The creator explains a four-step financial framework for retiring in one's 30s. He presents four calculations as a numbered list: 1) determining the total investment needed, 2) the required monthly investment amount, 3) the size of an emergency fund, and 4) the maximum monthly spending on essentials. He concludes by emphasizing the importance of the final point and includes a call-to-action to follow for more content.

[02]

Simple outline

  1. 1Promise a desirable outcome
  2. 2Provide a diagnostic checklist
  3. 3Reveal the foundational key
  4. 4Issue a call to action

[03]

Related videos

[04]

Classification

Format
Concepts
Rapid Fire ListicleBreakdown
Elements
Text OverlayTitle Text HookFollow / Subscribe CTA

[05]

Hook analysis

What stops the scroll in the first 3 seconds

Title hook

How to retire in your 30s

Verbal hook

Take your monthly income and multiply it by 300.

Visual hook

A direct-to-camera shot of the speaker who immediately begins talking, combined with a large, bold title text overlay appearing on screen. The sequential appearance of a numbered list with calculations provides immediate visual progression.

[07]

Hook and payoff

The promise the opener makes, and how the video pays it back

Hook

The video opens with a title card stating a highly aspirational and desirable goal, 'How to retire in your 30s', immediately capturing the attention of viewers interested in financial independence.

Payoff

The narrative concludes by explicitly stating that the final formula is the most critical one to address first, providing the viewer with a clear, prioritized starting point and a sense of having unlocked the 'real secret'. This is followed by a direct call to action to follow for more content.

[08]

Narrative framework

The structural pattern this video runs on

Framework

The Diagnostic Checklist

To provide a simple, multi-step, self-assessment framework that allows viewers to instantly diagnose their standing on a complex topic using easy-to-remember formulas or rules of thumb, ordered from aspirational goal to foundational action.

  1. 1

    The Ultimate Goal Formula

    Presents the first calculation, which defines the total amount needed to achieve the aspirational goal. This sets the 'final boss' number, establishing the scale of the challenge.

  2. 2

    The Actionable Input Formula

    Presents the second calculation, which breaks the ultimate goal down into a recurring, manageable action (e.g., a monthly contribution). This makes the goal feel more attainable.

  3. 3

    The Security Buffer Formula

    Presents the third calculation, which establishes a necessary safety net or prerequisite. This grounds the aspirational plan in practical reality and responsible planning.

  4. 4

    The Foundational Constraint Formula

    Presents the final calculation, which defines the most fundamental and controllable variable that underpins the entire system. This acts as the 'master key' to the whole plan.

Themes

  • Financial independence
  • Early retirement
  • Wealth building
  • Budgeting

Techniques

  • Direct address
  • Listicle
  • Rule of thumb

Trends

  • Financial education (FinTok/Fin-IG)
  • Micro-learning

Post caption

Four numbers that tell you exactly where you stand and what you need to work on. 1. Monthly income x 300. That’s what you need invested before your portfolio can replace your job, based on withdrawing 4% a year. 2. Monthly income x 0.2. What you should be investing every month. Ten percent is the bare minimum, twenty is what actually moves the needle. 3. Monthly expenses x 6. Your emergency fund, kept in a high yield savings account instead of the market. Use expenses, not salary, or you’ll save more than you need. 4. Monthly income x 0.5. Your ceiling on rent, food, transport and bills. Go over it and every other number here gets harder. Which one are you furthest from? (Not financial advice, do your own research)
Text overlays

  • title · beginning

    How to retire in your 30s

  • informational · beginning

    1. $1,800,000

  • informational · middle

    2. $1,200

  • informational · middle

    3. $15,000

  • informational · middle

    4. $3,000

Transcript

Take your monthly income and multiply it by $300 That's how much you need invested before your money can replace your job. Take your monthly income and multiply it by tier That's what you should be investing every month. Take your monthly expenses and multiply it by $6 That's your emergency fund sitting in a high yield savings account, not the market. Take your monthly income and multiply by 0.5. That's the most you should be spending on rent, food, transport, and bills. And if you are above the last one, fix it worst. Every other number depends on it. And follow for more finance content from me.

Financial rules listicle with examples | Viral Hooks